Business
When the bank account changes nature
Long considered simple fintechs designed to attract a young and connected clientele, neobanks have profoundly reshuffled the banking sector. A breakdown of a shift that is gradually redrawing the future of the banking industry.

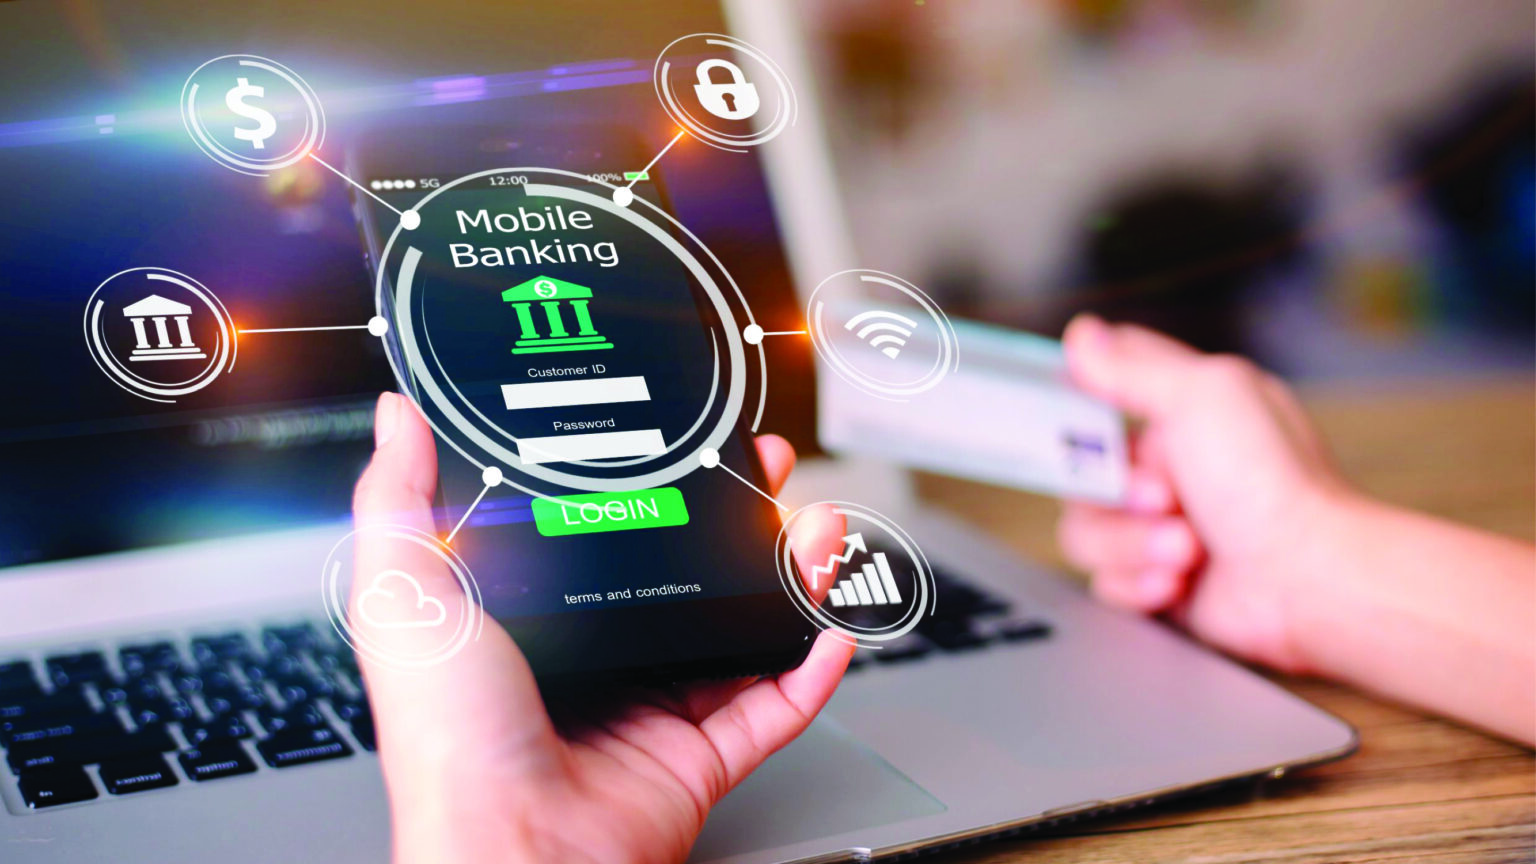
The banking revolution is no longer happening in branches. It is now happening on our smartphones. Every day, billions of transactions are carried out in a few seconds, often with a simple gesture on a smartphone.
Paying for a taxi, booking a plane ticket, sending money to a loved one, investing in the stock market, or paying for a purchase abroad no longer requires crossing the threshold of a bank branch. Financial services accompany each of our actions, but they are gradually disappearing from our field of vision. In just a few years, banking has begun to change nature.
For more than two centuries, its power rested on three pillars: a branch network, the ability to finance the economy, and the trust inspired by its brand.
This model, which structured the development of modern banking systems, is now being challenged by a transformation much deeper than the mere digitization of services.
The rise of neobanks is the most visible illustration of this. Yet reducing their success to a simple technological innovation would be a mistake. Their emergence mainly reveals that customer expectations had already changed.
Consumers are no longer looking only for a solid bank. They now expect a simple, instant, transparent service that is perfectly integrated into their digital daily life.
The real question is therefore no longer whether neobanks will replace traditional banks. It is to understand why they have managed to establish themselves in a sector that many considered one of the hardest to transform.
Why did neobanks appear at the right time?
Contrary to a widely held idea, neobanks were not born from a single innovation. They are the result of a convergence of several transformations that, for years, evolved separately before producing their effects simultaneously.
The 2008 financial crisis marked a first turning point. Beyond its economic consequences, it permanently weakened trust in part of the international banking system and led regulators to significantly strengthen their requirements in terms of capital, compliance, and risk management. While legacy banks focused on this deep reorganization, the digital world continued to accelerate.
The smartphone became the main access point to digital services. Cloud computing sharply reduced development costs. Application programming interfaces (APIs) made data exchange easier, while consumers got used to managing their daily lives through an app. Uses evolved faster than organizations.
This evolution is part of a much broader transformation of financial habits. According to the World Bank, nearly 80% of adults worldwide now have a financial account, compared with only 51% in 2011. This spectacular progress in financial inclusion has been accompanied by the massive adoption of the smartphone, which has become the main entry point to digital and banking services.
Taken separately, none of these factors would have been enough to disrupt the banking industry. Together, they created the conditions for a new model. This is precisely when players such as Revolut, N26, Monzo, or Nubank emerged. Their intuition was simple: if user behavior has changed, banking must be designed differently.
No longer from its internal constraints, but from its customers’ habits. This approach found a major echo in the market. Revolut alone now claims more than 70 million customers in more than 40 countries, compared with about 50 million at the end of 2024, illustrating the speed with which this new banking model has taken hold. This different starting point is gradually redrawing the rules of the sector.
Why did neobanks change the rules of the game?
Traditional banks did not ignore the digital revolution. Quite the opposite. For more than a decade, they have invested billions of euros in modernizing their information systems, developing mobile applications, and digitizing their processes. Yet these investments were not enough to prevent the rise of a new generation of players.
The phenomenon also goes far beyond Revolut. In Brazil, Nubank now claims more than 120 million customers, becoming one of the largest digital banks in the world. This success confirms that this transformation is not a European phenomenon, but a global one.
For legacy banks, digital was first and foremost a way to improve an existing model. New services were added to an organization built around branches, banking products, and sometimes outdated IT infrastructure.
Neobanks took the opposite approach. They imagined a bank designed directly for the smartphone, starting from their customers’ daily uses rather than from the constraints of their organization.
This difference in philosophy has profoundly transformed the banking experience. Opening an account no longer takes several days, but a few minutes.
Payments are instantly notified. Spending is automatically categorized. International transfers become simpler and more transparent.
Behind these features, it is not only the interface that changes. It is the relationship between the bank and its customer. Legacy banks were digitizing their processes, while neobanks were redesigning the user experience.
This nuance explains much of their success.
For a long time, banking competition was based on the quality of advice, the size of the branch network, or the ability to finance the economy.
Now it is also based on ease of use, speed of execution, and the smoothness of the digital experience. The standards set by major technology platforms have gradually imposed themselves on the financial sector. Neobanks have therefore not only won new customers. They have changed the expectations of all customers.
And when an innovation permanently changes market expectations, it ceases to be a competitive advantage. It becomes a new norm.
This evolution is now reflected in their economic performance.
In 2025, Revolut generated nearly 6 billion dollars in revenue and more than 2 billion dollars in pre-tax profit, confirming that the 100% digital bank model is no longer just a growth promise, but a profitable business. That is exactly what has happened.
Today, nearly all major banks are accelerating investments in digital journeys, instant payments, personalized services, and artificial intelligence. The innovations that used to set neobanks apart are gradually becoming industry standards.
But this transformation opens a new chapter. Because if neobanks have forced banks to rethink their relationship with customers, they may no longer be the only ones competing for that relationship. Tomorrow’s real competitors no longer come solely from the banking world. They are called Apple, Google, Tencent, or Amazon. And that is where the transformation changes scale.
The rise of neobanks marks an important stage in banking transformation. But it probably represents only one phase of this recomposition. The real battle is now shifting to a more strategic issue: control of the customer’s daily relationship.
Large technology groups understand this perfectly. Apple, Google, or Tencent do not necessarily aim to become banks in the traditional sense. Their goal is different: to integrate financial services into digital ecosystems where payments, savings, credit, or insurance become features among others.
In this logic, banking tends to become an invisible service, integrated into a much broader digital experience. This evolution represents a major challenge for legacy institutions.
Their competitive advantage no longer rests solely on their ability to gather deposits or distribute credit. It increasingly depends on their ability to offer a simple, secure, and personalized experience, while preserving what has always made them strong: trust.
This is precisely where banks still have a decisive advantage. Unlike technology platforms, they operate within a particularly demanding regulatory framework and play an essential role in financing the economy and ensuring the stability of the financial system.
Trust is not built solely through the quality of an app. It also rests on the strength of institutions, the protection of deposits, and the ability to manage risks.
For Morocco, this transformation represents both a challenge and an opportunity. The acceleration of digitalization, the progress of mobile payments, and the rise of the national digital transformation strategy create a favorable environment for financial innovation. This dynamic is reflected in the evolution of financial habits.
The latest World Bank data show continued progress in financial inclusion and the use of digital services in Morocco, confirming that consumer behavior is changing rapidly.
At the same time, Moroccan banks have important assets: recognized expertise across the African continent, significant investment capacity, and a regulator that is gradually supporting this shift without compromising the sector’s stability.
Ultimately, neobanks may not have revolutionized banking.
They have mainly revealed that a model built over more than two centuries had to evolve to respond to new uses. That is probably their main legacy. The banks of tomorrow will not be only those that finance the economy. They will be those that succeed in combining innovation, simplicity, and trust.
Because in a universe where technologies constantly evolve, trust remains the true strategic asset. In a world where technology evolves at high speed, trust remains the true strategic asset of banks. What is changing today is not its value. It is the way it is built.
The five features of a neobank
What sets them apart from traditional banks
- 100% mobile: account opening and transaction management directly from a smartphone.
- Simplified user experience: smooth journeys, real-time notifications, and intuitive spending management.
- More transparent pricing: lower fees and clearer visibility over the services offered.
- Rapid deployment: a digital infrastructure that facilitates international expansion without a branch network.
- Continuous innovation: rapid integration of new features (virtual cards, instant payments, budgeting tools, etc.).