Kingdom
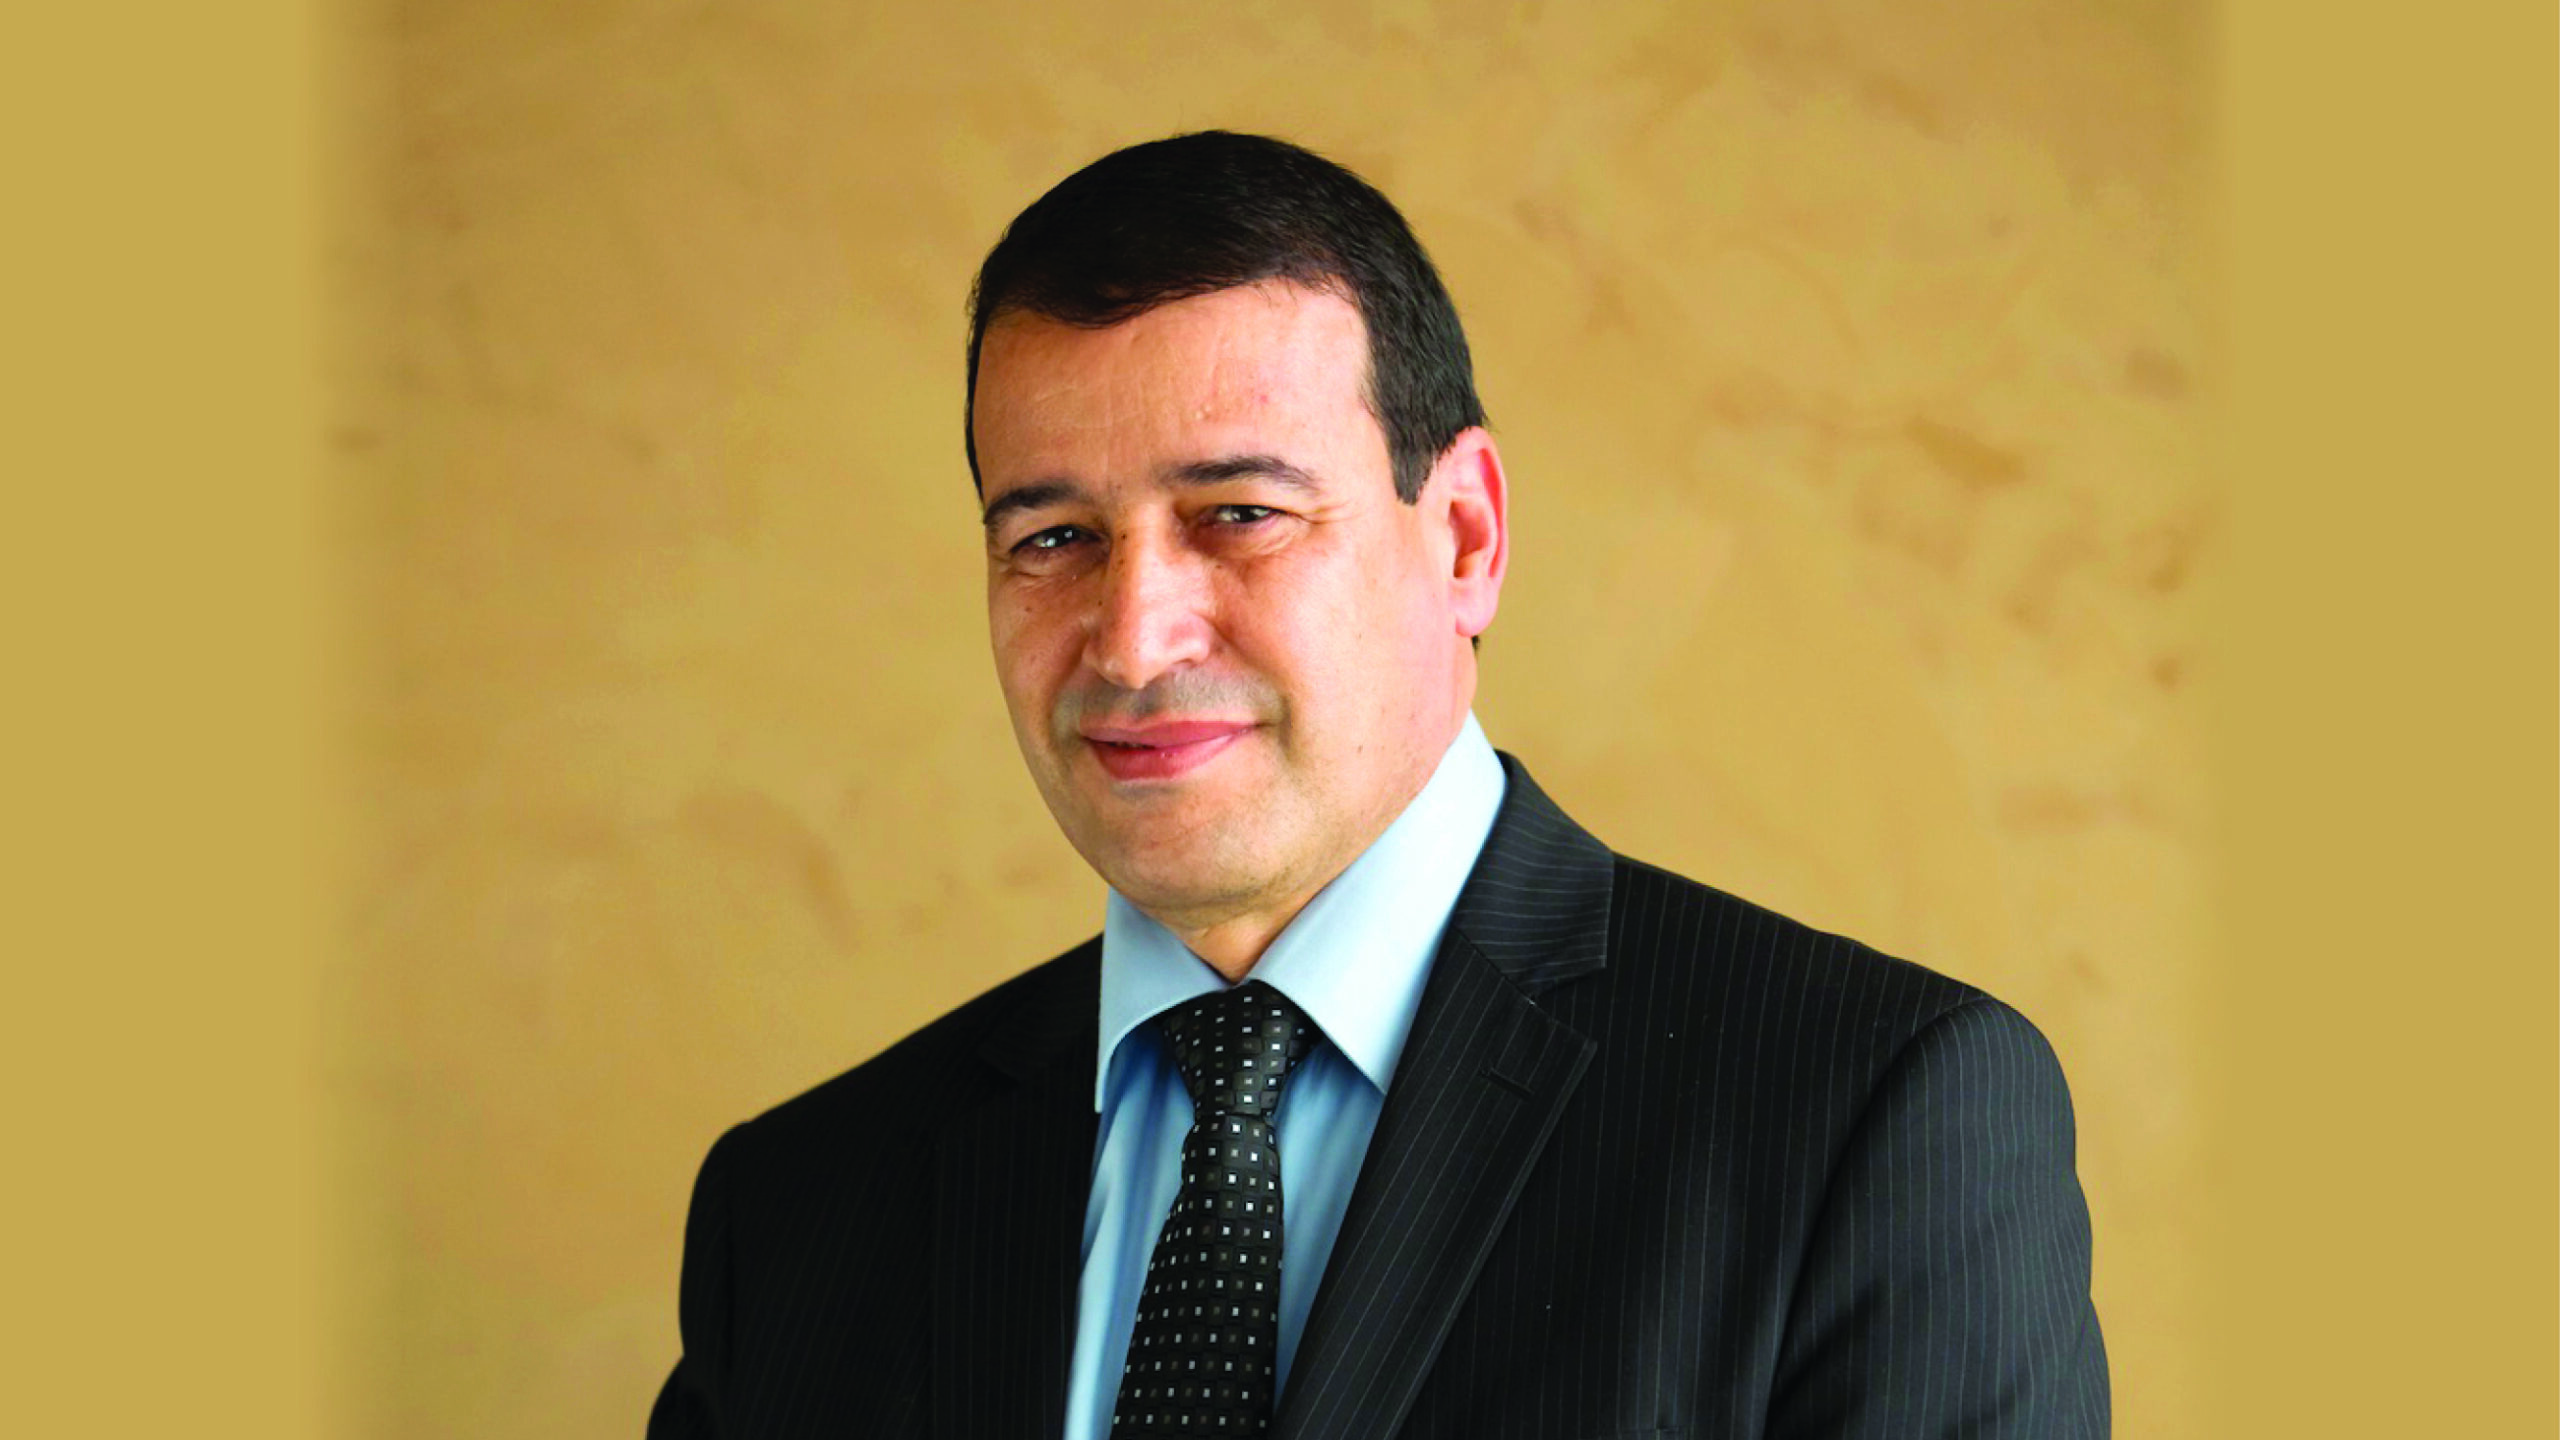
Mohammed El Baraka: “The Youth and Modernity of Our Olive Grove Are an Asset”
After two difficult seasons, olive production could exceed 2 million tonnes for the 2025-2026 season. This positive momentum is expected to boost olive oil production. Details from the president of the Moroccan Olive Oil Federation (FeHOM).

Despite abundant rainfall recorded this season, speaking of a definitive exit from the crisis for the olive oil sector would be premature.
Producers continue to face several structural challenges. In this interview, the individual who also serves as president of the Interprofessional Federation of Oilseeds (FOLEA) and the Professional Association of Oil Manufacturers in Morocco (APFHM) addresses several crucial areas related, among other things, to market prices, the current season, and Morocco’s positioning relative to the main producing countries of the Mediterranean.
After several difficult seasons marked by successive droughts, can we say that with the abundant rainfall this season, the Moroccan olive oil sector has lifted its head above water?
The rainfall recorded this season is undeniably a breath of fresh air for the olive sector, after several consecutive seasons marked by a severe water deficit.
It has had a particularly positive impact on rainfed orchards, which represent the majority of the national olive grove and whose production depends directly on rainfall. These inputs have helped improve short-term prospects and contributed to the partial replenishment of water reserves.
However, the situation remains more contrasted in irrigated perimeters, particularly in regions like Tadla and Haouz where constraints related to water availability, its cost, and pressure on water resources persist, despite the recent improvement in climatic conditions.
Furthermore, it would be reductive to limit the sector’s difficulties solely to water stress. Producers continue to face other structural challenges, including rising production costs, a shortage of agricultural labor, market volatility, as well as the resurgence of certain pests and diseases, exacerbated by the effects of climate change.
In this context, speaking of a definitive exit from the crisis would be premature. The challenge is rather to set the sector on a path of sustainable resilience, through integrated responses combining efficient water management, improved productivity, sector structuring, and better control of economic and health risks. This is precisely the logic guiding Interprolive’s actions.
For the 2025-2026 season, what are the production forecasts?
Based on field surveys conducted by the relevant services and the evolution of the national olive grove, the outlook for the 2025-2026 season is generally encouraging. After two difficult seasons, national olive production could exceed 2 million tonnes, an increase of over 110% compared to the previous season.
This positive momentum is explained by favorable agro-climatic conditions, including the satisfaction of the olive tree’s chilling requirements during winter, as well as abundant and well-distributed spring rains coinciding with the critical stages of flowering and fruit set. It is also driven by the gradual entry into production of plantations established under the Green Morocco Plan, which have now reached maturity.
On this basis, national olive oil production could reach around 200,000 tonnes, a significant rebound compared to the previous season.
These are, however, cautious estimates, closely dependent on maintaining favorable climatic conditions until the end of the harvest, controlling water and health-related uncertainties, as well as the availability of other determining production factors, particularly logistics and labor.
What were the highlights of the 2024-2025 season?
The 2024-2025 season took place in a generally constrained context but was marked by several salient facts. Despite limited production volumes, the quality of the oils produced was generally exceptional, praised by both professionals and at international competitions and contests.
This recognition confirms the know-how of Moroccan producers and operators, particularly in orchard management, harvesting, and milling.
Furthermore, the sector demonstrated notable resilience in exports, in an international environment marked by strong competition and high market volatility.
Exports managed to hold steady, reflecting a growing recognition of the quality of Moroccan olive oils in certain high-value-added segments.
Finally, this season was marked by the continued modernization of the sector, with broader adoption of improved practices both at the orchard and milling unit levels.
This axis remains central to Interprolive’s action to durably strengthen the sector’s competitiveness.
What is your assessment of price levels on the national market?
The price levels observed on the national market follow a classic supply and demand logic, in a context marked by several successive low-yield seasons, as well as a significant increase in production costs, particularly those related to inputs, energy, and labor.
At the beginning of the current season, olive oil prices were generally in a range between 55 and 80 dirhams per liter, with a national average price approaching 75 dirhams per liter, a decrease of about 20% compared to the previous season. However, with the gradual improvement in market availability, prices have eased further to settle, in some areas, within a lower range of 40 to 60 dirhams per liter.
This evolution, while contributing to improved product accessibility for the consumer, weighs on the income levels of small producers, particularly in the main production basins, such as Fès-Meknès, the Oriental region, and Marrakech-Safi, where prices generally remain below the national average.
In the medium term, the expected increase in production volumes, combined with better organized marketing and more effective sector structuring, should favor a gradual stabilization of prices, allowing for both fairer remuneration for producers and the preservation of consumers’ purchasing power.
Finally, what is Morocco’s position relative to the main Mediterranean producers?
Morocco today occupies a leading position among the world’s major olive oil producers, ranking fifth behind Spain, Italy, Tunisia, and Greece. This performance is the result of sustained investments and a proactive strategy for sector development over the past two decades.
One of Morocco’s main assets lies in the youth and modernity of its olive grove, among the newest in the Mediterranean basin, as well as the still significant potential for improving agronomic performance.
The current challenge, however, is no longer purely quantitative. It is now qualitative and economic, with the objective of strengthening the valorization of Moroccan oils, particularly in the segments of superior quality and terroir oils.
The development of geographical indications and protected designations of origin constitutes, in this regard, a strategic lever for sustainably improving Morocco’s positioning in international markets.