Business
Crédit du Maroc: After Consolidation, Acceleration
The banking group is beginning to reap the benefits of the transformation program launched since it came under Holmarcom’s ownership. After a solid 2025 financial year, it is now looking ahead to a new phase of acceleration to meet—or even exceed—the targets set out in its roadmap.

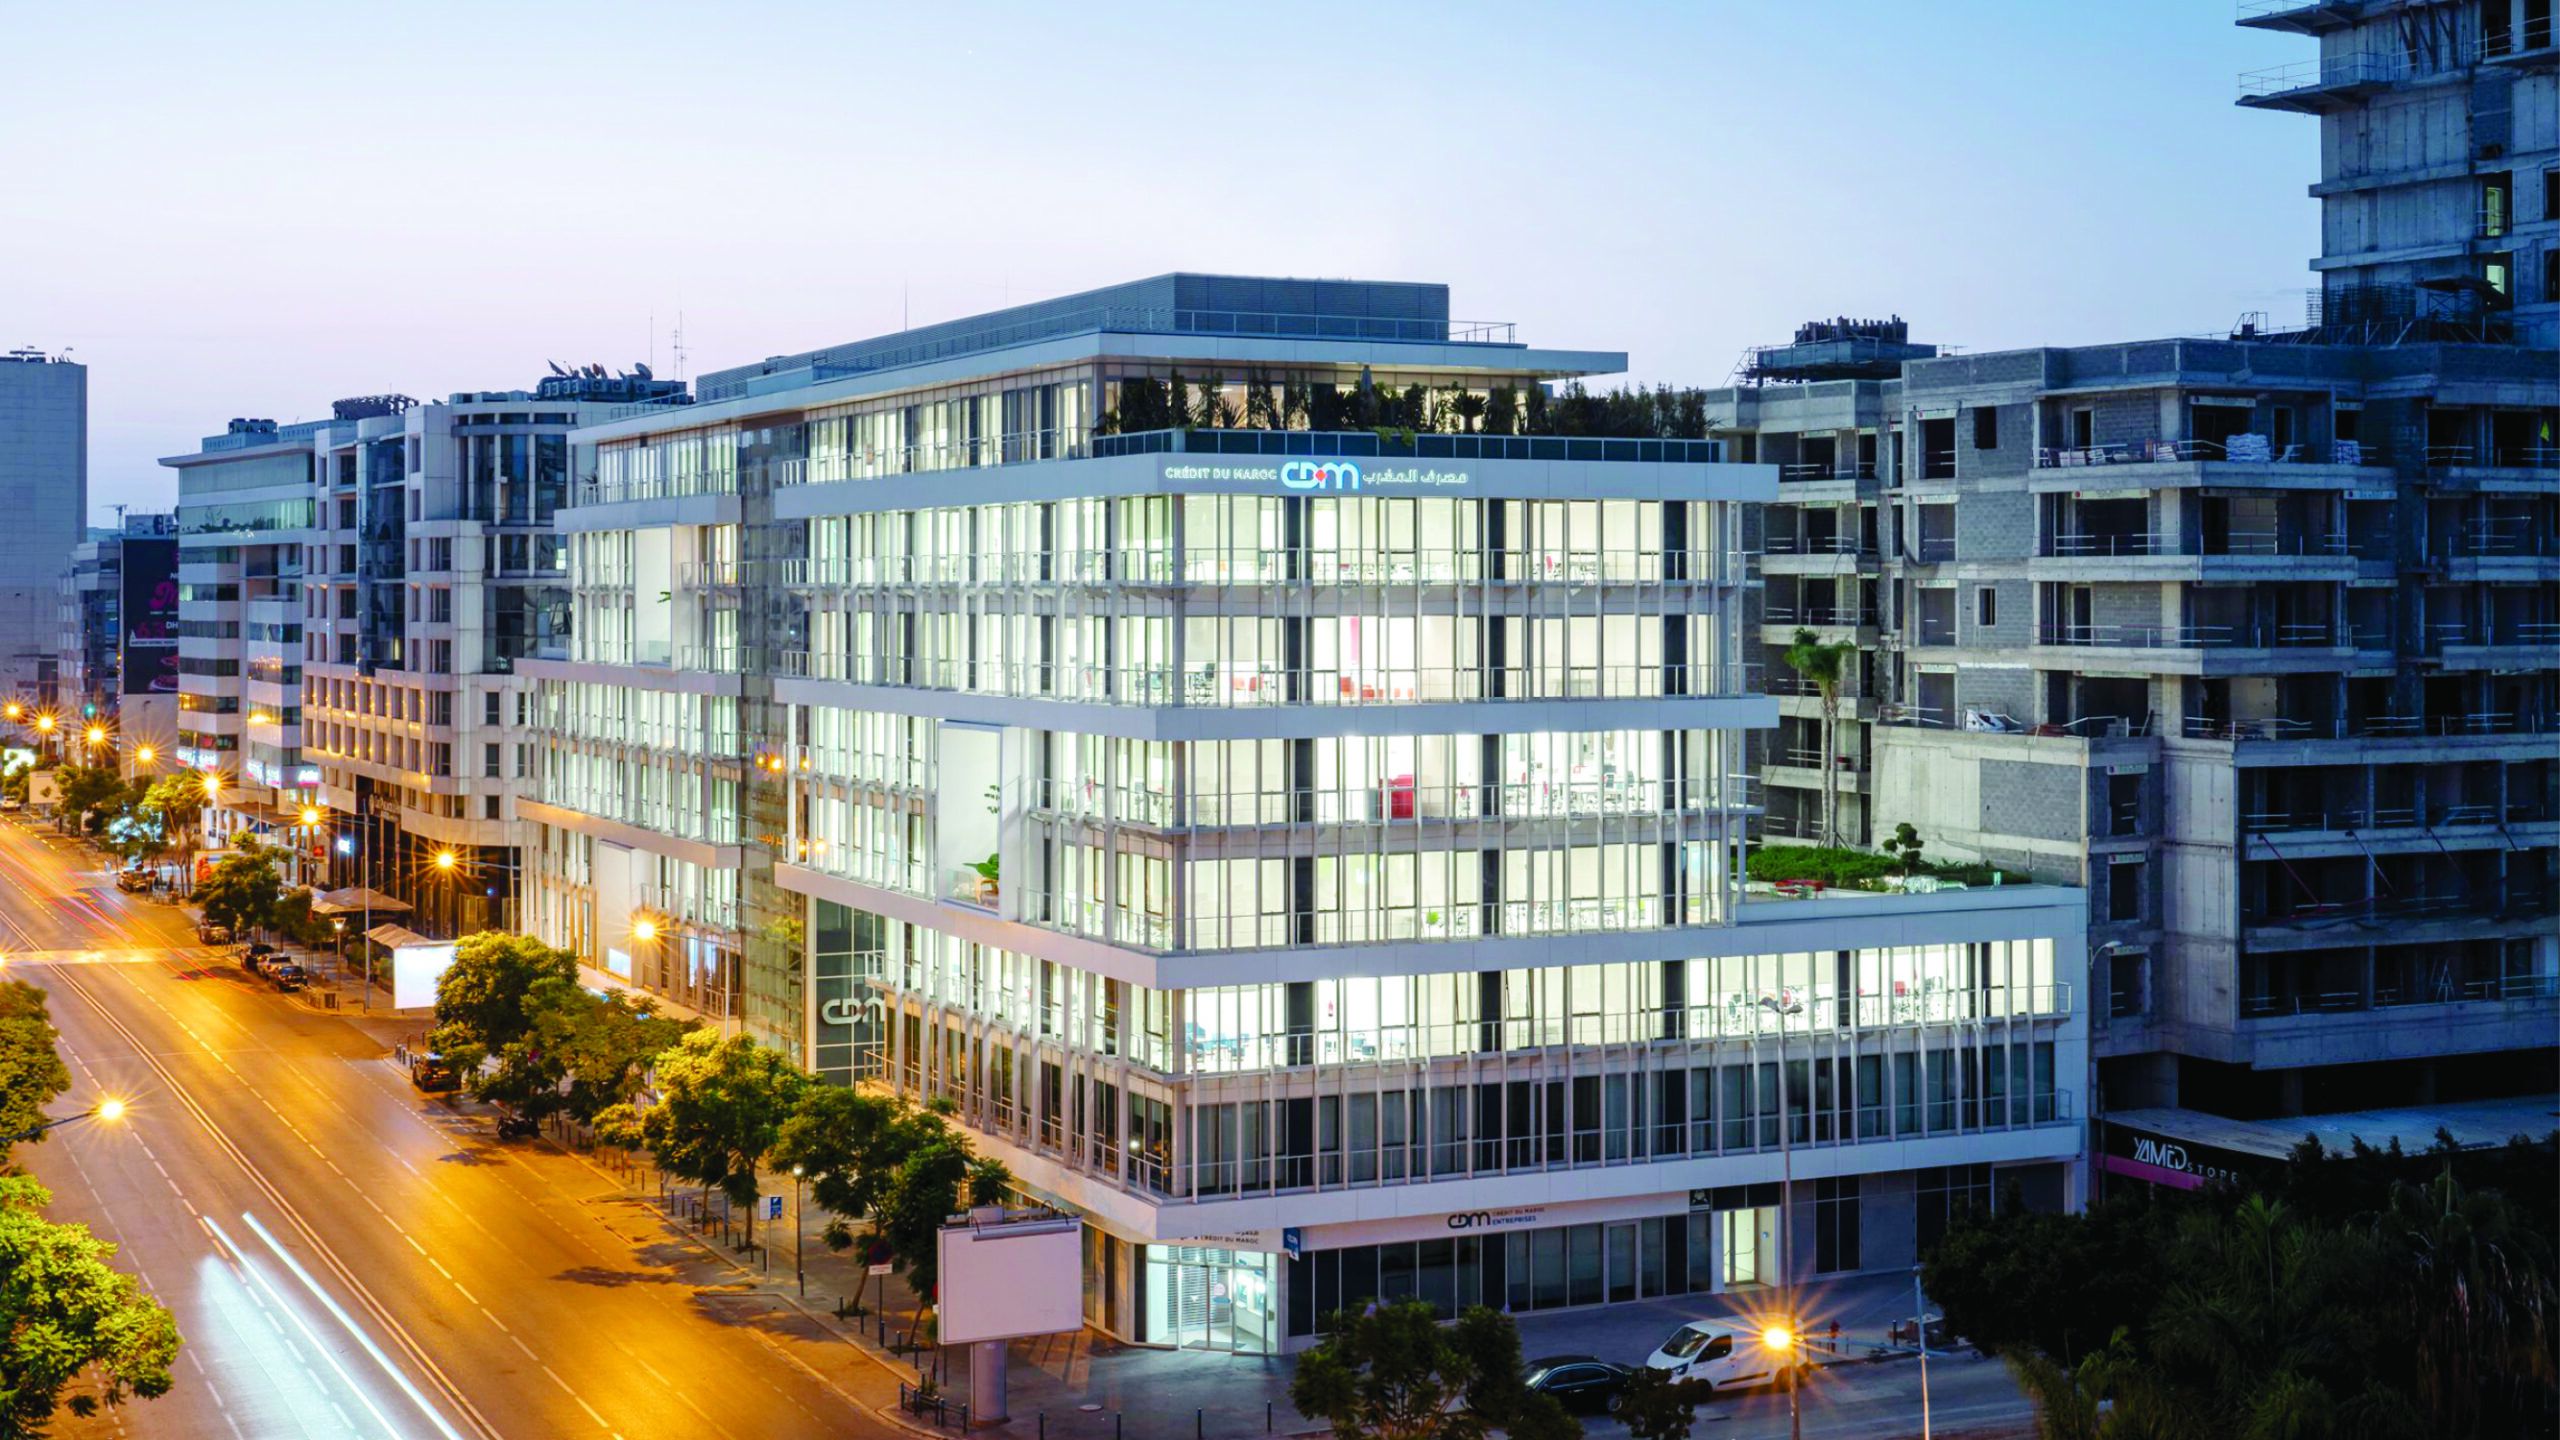
Crédit du Maroc is feeling a surge of momentum. The almost century-old bank, controlled from 2006 to 2022 by Crédit Agricole France, has enjoyed a second youth since it was taken over by the Holmarcom Group, the holding company of the Bensalah family.
After a transition period and a move toward greater autonomy from its former parent company, the bank has adopted a new, ambitious roadmap looking ahead to 2028, reflecting the ambitions of its new reference shareholder.
Entitled CDM Boost 2028, this roadmap marks a radical shift in the bank’s strategic positioning which, in short, moves from defensive to conquering.
Less elitist and more firmly rooted in the national economy, the bank is now targeting the middle classes and SMEs more strongly. It is also positioning itself across the full range of business lines, with new ambitions in consumer credit, leasing, and investment banking.
A true universal bank, in a way. This across-the-board growth strategy is accompanied by investment efforts to modernize digital infrastructures and improve processes. The target set for 2028 is clear: to reach 4 billion dirhams in revenue, 1 billion dirhams in profit, and 900,000 customers.
To achieve this, an action plan built around four pillars has been developed: accelerating commercial momentum, transforming the operating model, rigorous risk management, and employee engagement.
Commercial breakthrough
The least one can say is that the bank is on track to achieve these goals—or even exceed them. That is, in any case, what emerges from the 2025 annual results recently presented by top management.
Revenue as of the end of December in fact peaked at 3.56 billion dirhams, up 8%, while net income attributable to the group recorded a 16.5% increase, reaching 864 million dirhams.
Commercial momentum is strong, both in lending (+11%) and in deposit collection (+7.4%). Above all, the new growth drivers are delivering. In the corporate segment, loans for corporate customers’ equipment investment increased by 16.6% in 2025 after having surged by 25% in 2024.
Loans to property developers are following the same trajectory, with increases of 12.5% in 2024 and then 15.6% in 2025. “We have doubled our market share in this segment,” CDM notes. The leasing business, whose outstanding amounts did not exceed 400 million dirhams just a few years ago, posted outstanding balances up 42% in 2025, reaching 3.58 billion dirhams.
Among the other identified growth drivers, consumer credit for individual customers made a notable breakthrough with an 11.2% increase in outstanding amounts. The same is true for bancassurance, boosted since early 2025 by the partnership concluded with AtlantaSanad, another Holmarcom subsidiary.
“Crédit du Maroc is today experiencing a very positive evolution across all indicators. Revenues have been rising significantly for three years, driven by all business lines, whether historical or new,” Ali Benkirane, Chairman of the Management Board of the banking group, summed up at a press conference.
Today, he added, “we believe we have achieved nearly two-thirds of this trajectory, which confirms the relevance of our roadmap and the strength of our model.”
This performance, he insisted, “is not cyclical.” It is the result of work undertaken by the bank over the past three years: strengthening teams, stabilizing processes, improving operational efficiency, and so on.
For the bank’s top management, the ground is now prepared to begin a new phase of acceleration, with a strong focus on execution and service quality. “We have put the foundations in place, in terms of the operating model, the technological base, the HR framework, expertise, and ease of functioning.
These foundations will allow us to launch, starting in 2026, a new phase of acceleration,” the Chairman of the bank’s Management Board stated. The objective by 2028 is clear: “To position CDM as a major bank in the market—modern, innovative, simple, efficient, and above all solid and sustainable.”
Growth and discipline
But growth necessarily means controlled growth. There is no question of cutting corners on risk management. The executives say they are continuing an anticipatory and prudent policy.
“We do not choose between growth and risk control. The two move forward together, with a risk-management discipline deeply rooted in our DNA and prudent provisioning.”
In 2025, in a context of improving risk conditions at the national level, the cost of risk fell by 3.8% to 383 million dirhams. The coverage ratio for non-performing loans stands at 89.5%, up 206 basis points compared with 2024—an elevated level that reflects “provisioning to the highest standards.”
Nor is there any question of compromising the profitability of this growth. While the investment effort remains strong, with 248 million dirhams committed in 2025—mainly devoted to continuing its technological transformation—operating expenses remain under control, having risen by only 3%.
This performance translates into an improvement of 228 basis points in the cost-to-income ratio, which stands at 46.3%, thereby approaching the sector average.
It should be noted that the Management Board will propose to the ordinary general meeting the distribution of a gross dividend of 48 dirhams per share, up 15% compared with 2024. “We have a prudent dividend policy, with a payout of 65% of earnings. This helps strengthen our equity,” Benkirane explains.
Prudential ratios are consequently strengthened: the Tier 1 ratio stands at 12.5% and the solvency ratio at 14.85%. “We are ahead of the standards that will come into force,” the executive says, referring to the new regulatory requirements planned for 2027 with the rollout of SREP, a reinforced prudential supervision process implemented by Bank Al-Maghrib.
CDM Pay: promising first steps
The 2025 financial year was marked by the launch of CDM Pay, a new subsidiary specializing in electronic payment solutions dedicated to merchants and very small and medium-sized enterprises.
In a context of reform of the electronic payments market driven by the Competition Council, the structuring of this subsidiary was accelerated. “We quickly put together a dedicated team within the subsidiary, with a dedicated commercial setup, deployed to merchants,” Benkirane indicated.
The first results are considered satisfactory, with market shares exceeding 7% on the portfolios taken over from partner CMI. Beyond acquisition, CDM Pay is expected to become a strategic lever to position Crédit du Maroc among the leading payment operators in Morocco.