Kingdom
Aradei Capital: Diversification, Growth, and Move Upmarket by 2030
The property company has met its commitments and delivered results in line with its business plan at the time of its IPO. It is setting out an ambitious medium-term roadmap, targeting revenue of over MAD 1 billion and a portfolio valued at MAD 11.3 billion.

With a portfolio spanning around eight asset classes and totaling 35 assets, a valuation reaching MAD 8 billion, and a gross lettable area (GLA) of 506,000 sq m, Aradei Capital has successfully pursued a strategy combining growth and diversification.
Initially focused on retail, the property company has gradually expanded its scope into new strategic asset classes, notably healthcare, which now accounts for 18% of its portfolio with six operational clinics; ready-to-wear apparel, representing 12%; food service and leisure, 9%; industry, 7%; high-street retail, 5%; and offices, with a small 1% share.
This diversification concerns both asset types and geographic footprint. The company is present in 23 cities nationwide, though 20% of the surface area is concentrated in Casablanca.
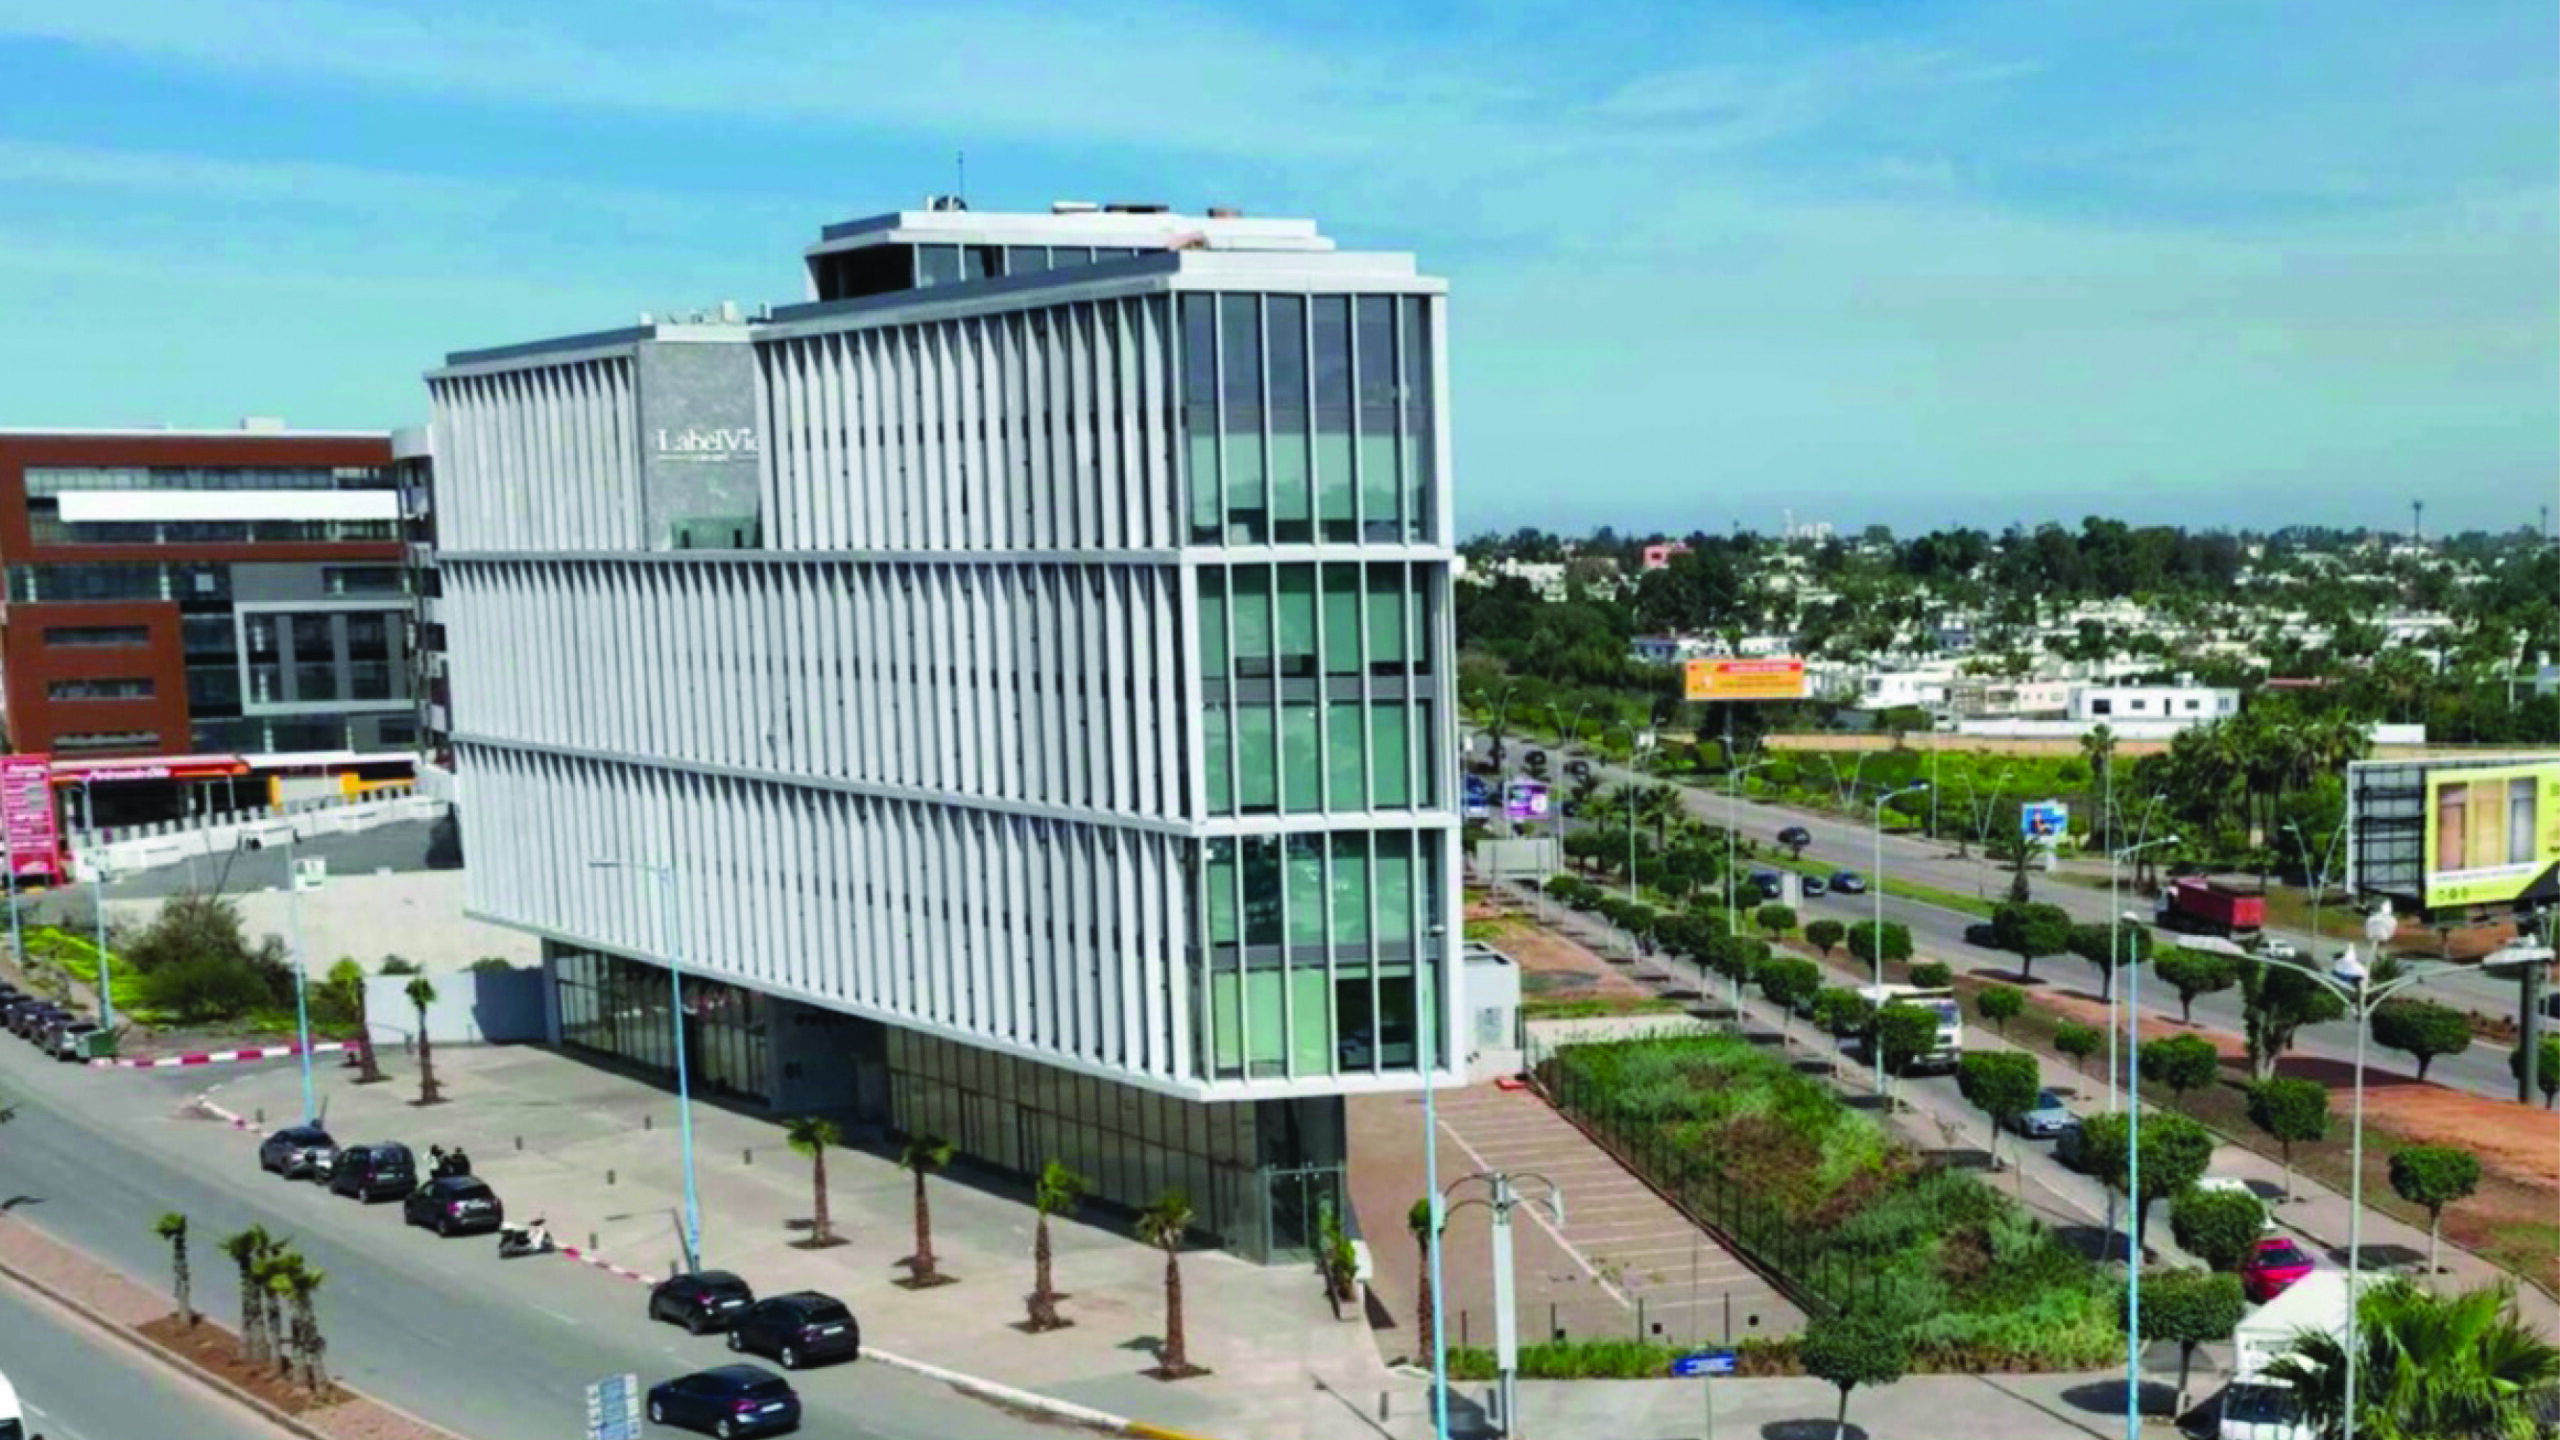
In addition, a flagship mixed-use (offices and retail) project is being rolled out at the entrance to the city, with a floor area of 60,000 sq m. “Scheduled to open in 2028, this strategic project includes 20,000 sq m dedicated to offices, 40,000 sq m to retail, and 1,800 parking spaces,” explained Nasser Benjelloun, CEO of Aradei Capital.
The occupancy rate stands at 97%, and the company faces no collection constraints, as the collection rate is also above 97%. This is explained by the quality of its tenants.
Aradei Capital relies for 57% of its rental income on three main partners: LabelVie (32%), Akdital (16%), and BMCI (9%). The rest of the portfolio remains granular, with 600 leases and 300 brands. It should be noted in this context that all other tenants each individually represent less than 5% of rents.
Ambitious action plan
Aradei Capital intends to continue this strategy by implementing an ambitious roadmap through 2030, based on a sustained growth momentum driven by portfolio diversification, disciplined financial management, and a clear strategic vision.
The asset portfolio would thus be valued at MAD 11.3 billion. Revenue would be multiplied by 1.8 compared with 2024 and is expected to reach MAD 1.1 billion, with FFO (Funds From Operations, or recurring net income) of MAD 500 million (1.6x versus 2024).
In this context, the EBITDA margin would be maintained above 70% and the distribution rate would be around 85%. These ambitions are accompanied by an investment program of MAD 3.3 billion through 2030, including MAD 1.8 billion secured with an 11% yield on cost, plus a MAD 1.5 billion pipeline under review.
This program includes, in particular, the launch of Sela Park Casablanca—bringing the total to eight across the country—as well as the development of mixed-use assets in Casablanca.
This is in addition to continuing the diversification strategy into new asset classes and unlocking value from the land bank. In this respect, Aradei Capital plans to launch a modernization program for Al Mazar in Marrakech (37,000 sq m) and Borj Fez (27,000 sq m), with an investment of MAD 120 million and delivery expected during this half-year.
“Contrary to common belief, the retail business remains profitable and would continue to represent a strategic pillar in our growth plan… and even more so in Fez and Marrakech, where commercial activity is thriving,” assures Nawfal Bendefa, Chairman of Aradei Capital’s Board of Directors.
Other levers will also be activated. They include strengthening the leisure offering under the WAW brand and the launch last October of a retail media agency, “Elevate,” offering bespoke, high-impact solutions across the portfolio.
“The share of this segment in revenue is around 5% and should ultimately reach 12%. Our objective is not to make this segment one of our main businesses,” Benjelloun explains.
However, Bendefa believes these forecasts—conservative and therefore realistic—do not take into account certain opportunities not yet secured or additional development avenues.
Deliveries in line with the business plan
Since its stock market listing in December 2020, Aradei Capital has posted a growth trajectory described by management as accelerated. Between 2020 and 2024, GLA increased by nearly 37%, driven by approximately MAD 2.3 billion in additional investments and an active acquisitions and development policy.
The portfolio valuation, for its part, rose by nearly MAD 3 billion, combining investments and the revaluation of existing assets. Financially, key indicators point to a clear strengthening of fundamentals.
Revenue came in at MAD 606 million versus MAD 271 million in 2020; EBITDA increased from MAD 214 million to MAD 450 million; and group share of FFO more than doubled over the same period, reaching MAD 305 million.
This progress was achieved within a controlled financial framework, with an average cost of debt of 4.6%, a maturity of more than six years, and limited exposure to interest-rate risk, given that 82% of debt is fixed-rate or capped. Two-thirds of funding sources are bank financing, with the remaining third represented by bonds.
To support its development strategy, the gearing ratio increased in parallel, reaching 33% versus 22% five years earlier, without compromising the company’s solvency ratio, which stood at 3%—70 bps higher than before.
A dividend yield of nearly 5%
The growth strategy is also part of an enhanced ESG approach through the “Bricks for Impact” program. Environmental certification of assets, the energy transition, access to healthcare, community engagement, and best-in-class governance are among the stated priorities.
In fact, Aradei Capital is Morocco’s first Edge Champion company—an IFC-backed certification—with four assets already certified. Moreover, all its assets are fitted with LED lighting, and 1,300 solar panels were installed across three assets in 2024, delivering 25% energy savings. A further 14 sites will be equipped by 2030.
These efforts earned its inclusion in the MASI ESG index in 2024. On the stock market, the property company offers attractive valuations, with a P/E estimated at 15 in 2026 and a dividend yield of 4.9%.













