Business
Mohamed Filali: “The Moroccan Dynamic Accelerates, Driven by the Rise of Private Placements”
The Moroccan private debt market is experiencing a significant evolution, driven by the growth of private placements, increasing investor interest in yield products, and gradual opening to new issuers, notably SMEs. The expert’s perspective.

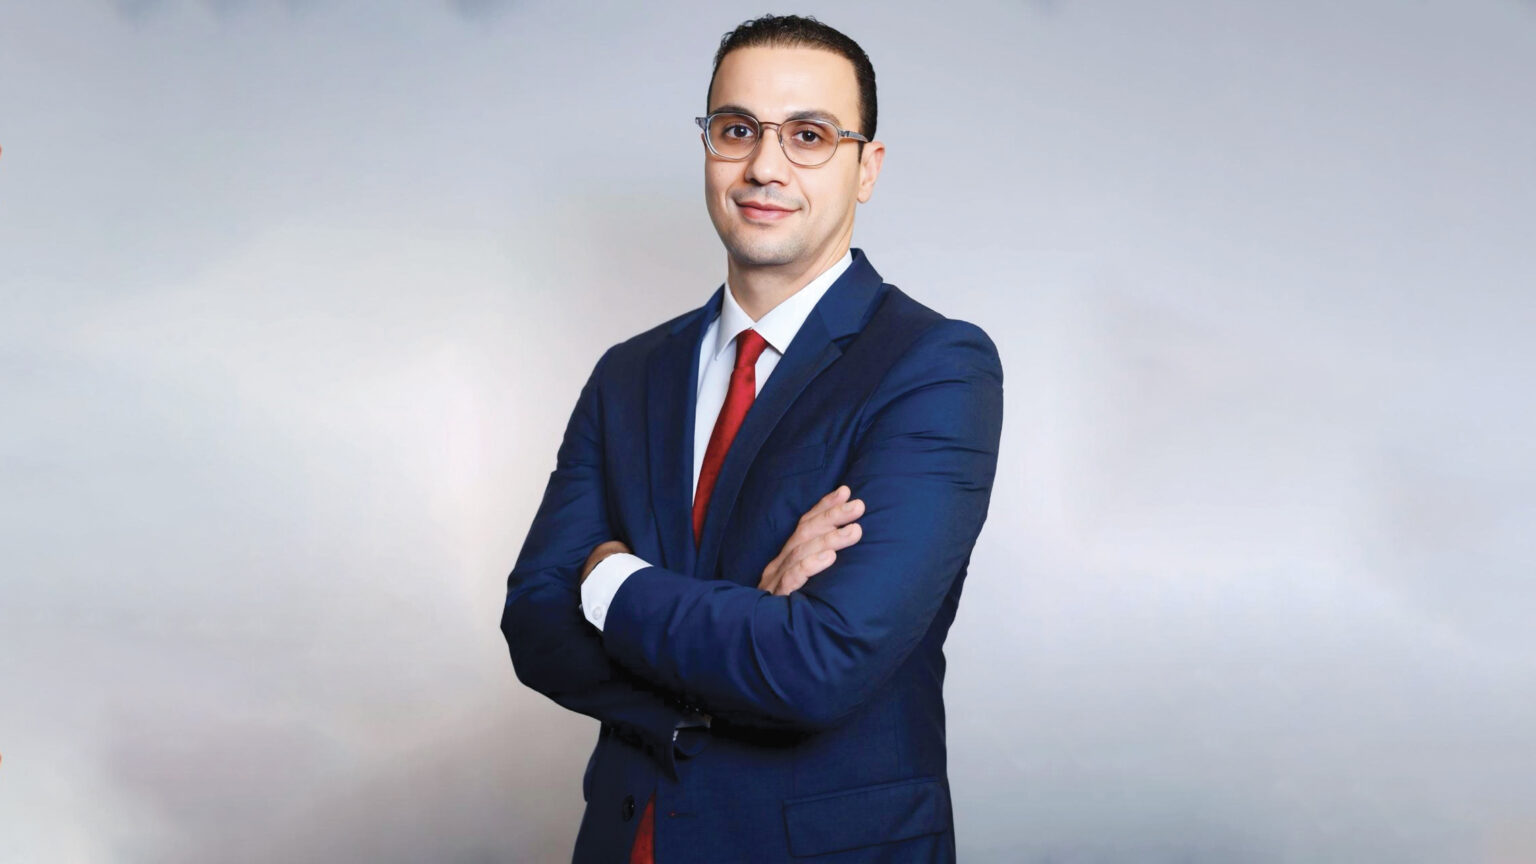
Mohamed Filali is an experienced finance professional with over 16 years in asset management and trading rooms. A finance graduate from Paris-Dauphine University, he began his career in Paris at ABN Amro and UBS before joining Attijariwafa bank in Casablanca in 2009. Since 2021, he has led market activities in Morocco. He is also president of the Moroccan Association of Trading Rooms (AMSM) and secretary general of the Interarab Cambist Association (ICA).
In this interview, he discusses the factors behind the momentum in the private debt market, its current limits, particularly in liquidity, and reforms to support its long-term structuring.
What explains the acceleration of private placements on the Moroccan private debt market in recent years?
This dynamic is mainly explained by three factors. First, Moroccan companies increasingly seek to diversify their financing sources. Second, local investors show strong appetite for instruments offering more attractive yields, especially in a persistently low-rate environment. Finally, private placements offer great flexibility both in structuring and in regular publication requirements, combined with simplified and accelerated issuance procedures at the AMMC.
How do private placement issuances differ from public offerings?
Private issuances target a limited circle of qualified investors, restricted to twenty participants per transaction. They do not require prior AMMC approval, although issuers must inform the authority beforehand, which has the right to oppose the operation. Public offerings target a broad audience, require mandatory AMMC approval, and impose prior publication of a detailed prospectus. Thus, private placements offer faster execution and notable flexibility compared to public offerings.
What is the current relative weight of private debt securities in Moroccan business financing?
In 2025, bank loans granted to Moroccan companies amount to 787 billion dirhams, while private debt outstanding reaches 338 billion dirhams, representing nearly 30% of total business funding. This ratio reflects a notable evolution in the Moroccan financial landscape, marked by a progressive diversification of financing sources.
The rise in private debt securities reflects both greater maturity of companies toward capital markets and an effective response to medium- and long-term financing needs.
This dynamic is supported by a constantly improving regulatory framework, increasing investor appetite for these securities, and the emergence of new investment vehicles. It also highlights the importance of continuing market deepening efforts to make it a true financing lever for growth, transparency, and economic resilience.
Have you noticed a notable evolution in the profile of issuers in recent years?
Yes, this evolution is particularly significant. Initially concentrated around financial institutions and a few large public entities, the Moroccan private debt market has gradually opened to a much more diversified typology of issuers. There is now growing participation from industrial SMEs and private non-listed groups.
This dynamic reflects increased maturity of Moroccan companies regarding market instruments.
In the medium term, major structuring projects related notably to the organization of the 2030 World Cup (in infrastructure, construction, logistics, or tourism) should further broaden the issuer spectrum and help strengthen this diversification.
Does the ESG factor now influence investor choices in the private debt market?
Indeed, the ESG factor is beginning to significantly shape investor choices. Several recent issuances show this trend, such as green bonds to finance solar energy projects or other bond issues focused on sustainable initiatives. However, this trend should be nuanced: for local investors, the current absence of a clear regulatory framework and specific incentives still hinders the development of this type of investment. For foreign investors, ESG criteria have become decisive, reflecting their growing sensitivity to these issues and positively influencing their participation in the Moroccan market.
How is the liquidity of the secondary market for negotiable debt securities evolving today?
Secondary market liquidity is gradually improving, notably driven by the development of market-making practices and increasing involvement of institutional investors. However, this improvement remains relative due to prevalent “hold to maturity” strategies that naturally limit trading volumes.
It should also be noted that liquidity of securities issued by private placement is intrinsically more limited, due to the very nature of these operations. These issuances are generally subscribed by a small number of investors, which reduces the depth of the secondary market for these instruments. Furthermore, internal constraints for many funds or financial institutions limit their capacity to actively trade these securities, further restricting overall segment liquidity.
What trends do you currently observe regarding private bond rates and spreads?
There is currently a notable compression of spreads on private debt, a phenomenon directly linked to strong demand for these instruments in a context of gradually easing interest rates.
Yield-seeking remains strong among institutional investors, in an environment where opportunities offered by private debt remain attractive as a complement to the equity market, which, although currently performing well, does not alone cover all portfolio allocation needs.
This situation generates strong competition on new private debt issuances, contributing to lower spread levels.
What regulatory improvements would enhance security and boost this market further?
Certain regulatory improvements are needed to strengthen the depth, transparency, and attractiveness of the Moroccan private debt market. First, systematic use of issuer ratings by specialized agencies should be encouraged to build investor confidence and improve risk clarity.
Additionally, developing a structured platform dedicated to the secondary market for negotiable debt securities would significantly enhance liquidity in this segment, facilitating a wider range of investor participation.
In the same spirit, specific measures to promote SME access to these instruments, taking into account their particularities, would be relevant. Finally, it is important to strengthen the culture of regular financial communication and transparency by issuers, an essential condition to consolidate a credible and sustainable market.